

Suppose you get a $1,000 payment. How much do you consume? Before answering, we’d want to know a few things: Is this a one-time payment? The first of many? Can you borrow? Do you already have savings?
This year’s Nobel Prize went to Robert Hall and Michael Woodford for providing the theory to make this concrete, the empirical work to test the theories, and showing how policy, optimal, and realistic differ depending on how we answer the theory and empirical questions.
When co-authors win the Nobel Prize, like in 2024, it’s pretty simple to see why they’re paired together. It makes a lot of sense.
This one takes a little more squinting. Michael Woodford is a perennial favorite to win, and Robert Hall is one of the great economists of all time, but is less mentioned in Nobel discussions.
The Nobel Committee found a way to tie them together for “micro foundations of macroeconomic stabilization.” I would say it’s “microeconomic foundations of macroeconomics,” but my guess is that that doesn’t seem important, so they wanted a “why does this matter?” hook, so they went with “stabilization,” which immediately connects to policy.
This is a great macro prize. It’s partially a New Keynesian prize. Woodford is basically synonymous with New Keynesian economics, although Hall is less often described that way. As we’ll see, Hall’s equations and empirical approach became an essential part of the New Keynesian model.
I’ll go through some of Hall’s contributions: those directly connected to the prize, but also some that the committee left out that I think are equally important and interesting. Then I’ll talk about how that laid the foundation for Woodford’s work, which has been central to macroeconomics for 20+ years.
Consumption, today and tomorrow
Going back to the $1,000 question, every question I ask is really getting at the same point. What does the payment tell you about your future income? A household that can borrow and save will be able to spread that windfall, if it’s one-time, over many years. A temporary payment is really a small change in wealth. News that your income is permanently higher is a very different situation. It could generate a large change in your wealth.
That distinction between temporary and permanent is what killed the old Keynesian consumption function, which tied spending to current income. Milton Friedman’s Nobel Prize is partly awarded for this, for his permanent income hypothesis. One of Hall’s contributions was to make it precise and check it against the data. Hall is squarely in the Chicago price theory tradition with this micro-macro connection.
The hard part, empirically, is that expectations matter in the other direction too. Suppose you learn today that you’re going to lose your job in 6 months. You may cut spending now while your paycheck hasn’t changed. When you end up losing the job, the income drop may not be very large, and your spending may barely move.
By the late 1970s, economists had been writing down this sort of problem with rational expectations. A household that cares about consumption every period chooses a path so that giving up a dollar today and spending what that dollar generates tomorrow are worth the same on the margin. That condition is the stochastic Euler equation, which is drilled into you in economics education.
In English, the left side is about what a dollar of consumption is worth today (the marginal utility of consumption). The right side is what a dollar is worth if you save it, earn the interest rate r, and spend it next period, discounted by your impatience beta. At the optimum, the two are equal. This is just the equimarginal principle (on the margin, equalize costs and benefits). What makes it slightly unique, makes it slightly macro, is that we have time, and, therefore, we have expectations.
Testing the model
A version of the stochastic Euler equation falls out of every modern macro model. Is it true? Does it show up in the data? Hall’s 1978 paper, “Stochastic Implications of the Life Cycle-Permanent Income Hypothesis,” turned this theory into something you could check.
The hard part is that you can’t observe what a household expects about future income. That expectation operator in the equation above is tricky. Hall’s insight was that you don’t need to know expectations. Under his benchmark, the level of consumption will follow a random walk, so changes in consumption reflect news. The basic idea is that anything households already know is in today’s spending, just like what the market believes about future earnings is in today’s stock price.
Today’s consumption is a very good predictor of tomorrow’s consumption. Nothing else should be. It should follow a random walk. The question is: if anything else that households already know, like last year’s income, improves, then incorporating that improves the forecast. If the theory holds, those extra variables shouldn’t improve predictive power at all.
Rather than being a clear victory for this version of the permanent income hypothesis, the evidence was mixed. Past income added little once consumption was in the regression, but stock prices were the exception, so we didn’t have a clear vindication or rebuttal of the model. What Hall did show was how to turn the theory about some unobservable expectations into a restriction on observable data. That’s a powerful connection from theory to data.
Do interest rates matter?
Going back to the Euler equation, Hall’s 1978 paper is really looking at that expectations operator and putting the focus there. That’s not the only thing on the right-hand side. We can also ask whether there is anything else we can pin down, beta, the personal discount factor.
We can also ask about the interest rate. If monetary policy works by moving that price, the price between consumption today and consumption tomorrow, we can estimate the size of that response. A higher expected real return makes postponing consumption more attractive, and the elasticity of intertemporal substitution measures how much that occurs.
Hall’s 1988 paper on intertemporal substitution goes after it. Now let’s look at the very fancy plots that one sees in an 1980s economics paper.
Each point is a five-year average of the real return from Treasury bills, plotted against the growth rate of consumption. A strong response to the interest rate would show up as an upward-sloping set of dots. That’s not what we see. To be clear, this is just a descriptive illustration. It’s not how Hall actually estimates the elasticity.
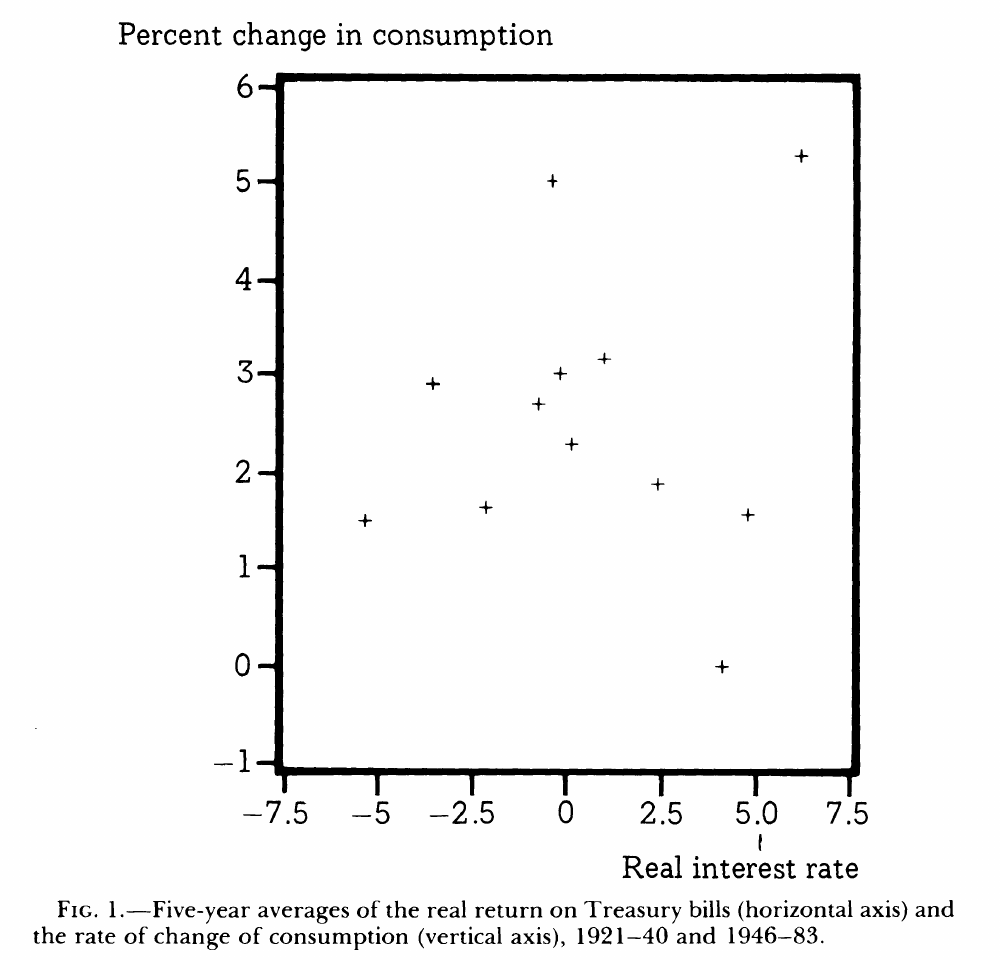
This plot of prices (interest rates) and quantities (consumption) has the usual identification problem: you’re only picking up equilibrium price and quantity, which could be moving around as supply or demand shifts. We instead want to pick up how quantity moves around given an exogenous change in r.
Hall’s solution is the usual one for any demand curve. You can’t just regress price on quantity, but you need to find a variation in the price that has nothing to do with the shocks to whatever it is that you’re explaining.
This is where the theory helps, where the Euler equation matters. It says households act on expected real return. Any variables that happen before the consumption change that help predict that return, like earlier interest rates or earlier inflation, are themselves information that the households could have used. They are not shocks or surprises to consumption. You can use those as instruments and ask whether the part of the expected return they predict lines up with consumption growth.
The measure of price needs care, too. The return that matters is the expected real return after taxes, not the realized one, so you’ve got to be careful with that. Hall spends a lot of his time in his career being precise about these things. This isn’t a post about the details of measuring post-tax returns. The important thing is that Hall filled in the details, moving from the model to the empirical implication.
So did the interest rate matter? Not really.
The elasticity could be zero, and it is probably no higher than 0.2. But this was a start of measuring this, not the tightest estimate ever. A 1988 paper with aggregate data is not the end of the empirical discussion, and as with many prizes, this one is about launching a whole research program. Hall’s weak elasticity leaves a puzzle. If households barely shift consumption across time when the real rate moves, how does a rate cut raise spending at all?
The wide-ranging Bob Hall
If you go to Hall’s Google Scholar page, you’ll see that these consumption papers are only his second and sixth most cited papers. He has done so much, including things like a popular optimization algorithm. As Tyler Cowen rightly put it, “Every Bob Hall paper is interesting!”
Let me focus on two that I think are core price theory.
Even if you buy the machine, you pay the rental price every period, because you could be renting it to someone else. Owning does not make its services free. Hall and Jorgenson (1967), written while Hall was a graduate student, built an empirical investment model on that idea. The sticker price is not the cost of using the machine for a year. The firm ties up money, the machine depreciates, and its resale price may change. The cost of using capital is roughly the price of the capital good times the interest rate plus the depreciation rate, less expected capital gains.
The firm compares what the machine adds to output with that user cost, and the paper estimates how much investment responds and when. It is the household problem again, with the real interest rate as the price of time.
The other paper is Hall’s 1988 JPE article on price and marginal cost. This is cited in the scientific background, but I’m pretty sure it’s a typo.
What does producing one more unit actually cost? Firms don’t report marginal cost, but we can observe how their inputs change when they produce more. The problem is that this tests competition and constant returns together. We are always doing a joint test, but that’s a topic for another day. But that is classic Hall. Let’s take something we don’t directly observe and work out how to test it using choices we do observe.
The markup paper, while cited by the Nobel committee but in a very confusing way, also sets up Woodford nicely, which has sticky prices and markups.
Woodford puts the pieces together
Suppose the central bank wants to know what happens if it raises the interest rate by 1%. Instead of the old approach of estimating how inflation moves with unemployment, you want to start with a microfounded approach (as the Nobel prize points out) of how households and firms are making decisions. Then you can make causal claims. You need to know what causes what.
The problem with correlations is that people’s behavior changes depending on the policies that they live under. This is the classic Lucas critique. In the 1960s, higher inflation came with lower unemployment, so policymakers tried to exploit that. People came to expect inflation. The 1970s gave us high inflation and high unemployment together.
Woodford’s contribution is that he tied the pieces into one causal chain. The Nobel Committee’s scientific background lays it out following his book Interest and Prices.
The benchmark New Keynesian model has just three equations.
The first equation is Hall’s Euler equation with some bells and whistles. Add some things about the “natural rate” à la Wicksell, and you basically have it.
The second equation comes from firms. A restaurant that reprints its menu once a year (just assumed because of sticky prices) has to guess at costs and demand for the whole year its prices will be in use. Firms that can’t change prices every period face the same problem, so their pricing looks forward.
Then you close the model with an interest rate rule. It sets its interest rate in response to inflation and the output gap, as in a Taylor rule, thereby closing the loop.
So you have all these three equations feeding back into each other. Every link is a choice someone makes. Everyone is looking ahead and thinking about the future, and when you change the rules, people change what they can expect. That trickles into their behavior. This allows us to work through responses, assuming people will behave as they did in the old policy. That is the benefit of microfoundations.
Does this particular microfounded macro model match the data? Yes and no.
Taking NK to the Data
Everyone knows the book, Interest and Prices, but the easiest way into the project is a 1997 paper with Julio Rotemberg. They built a quantitative model from optimizing households and firms and used it to evaluate monetary policy rules. The first question is whether the model can reproduce what happens after an unexpected Fed rate increase.
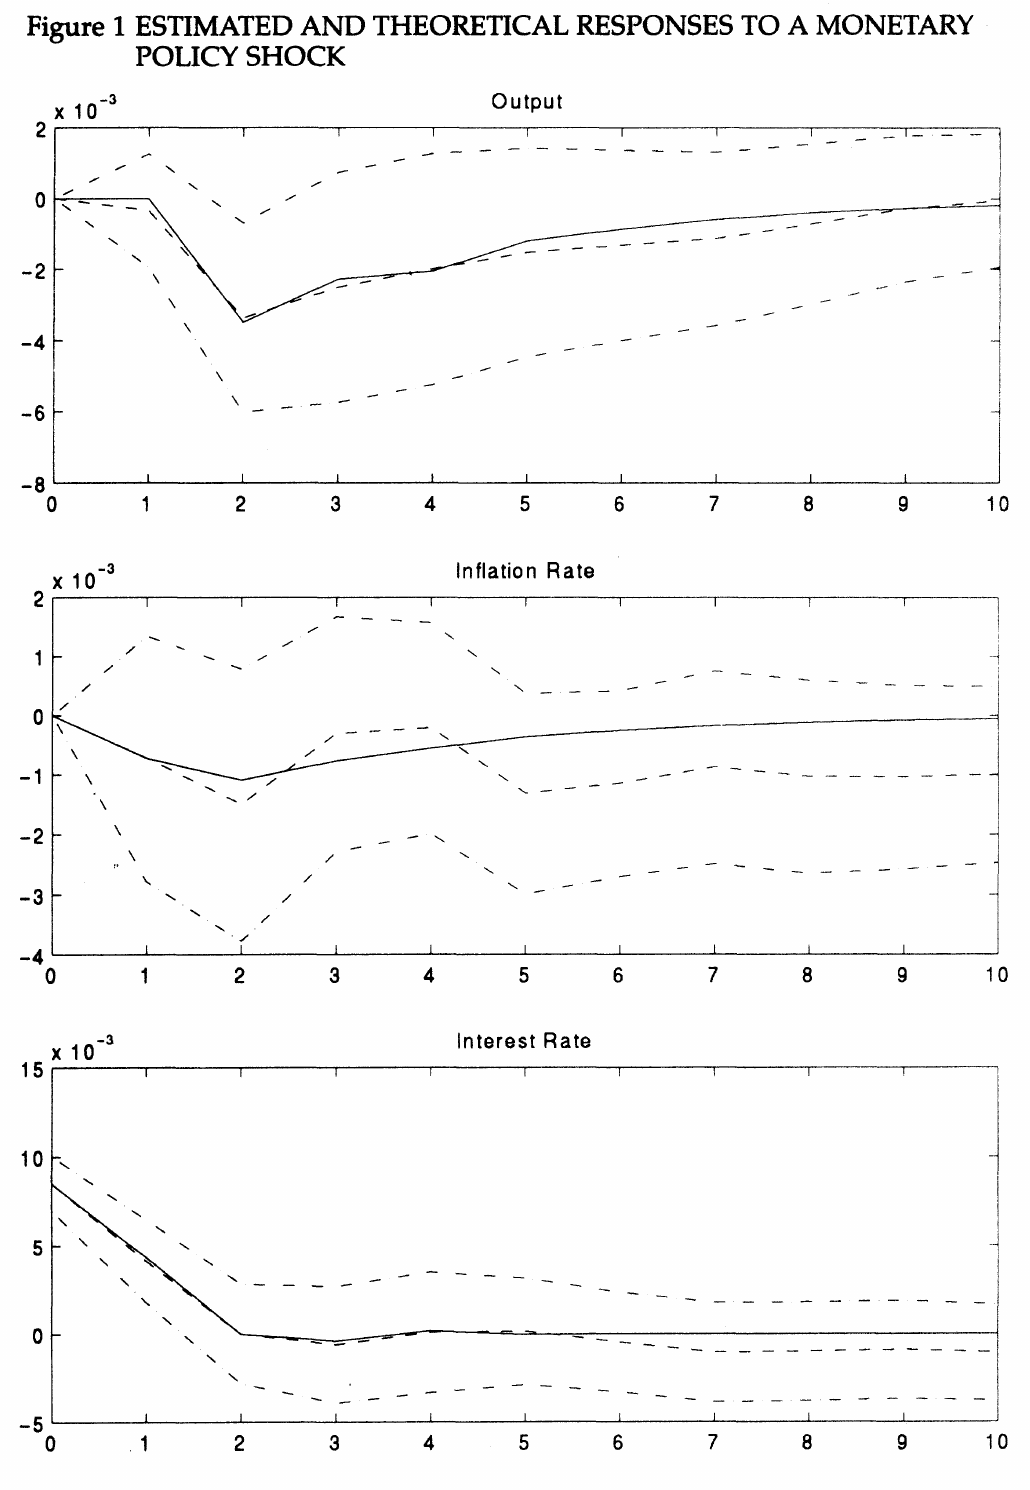
It’s a weird way of showing it, but the bottom panel shows the shock.
The interest rate rises and then returns to normal within a couple of quarters. In the top panel, the output falls with a delay and recovers gradually. The model’s solid line follows the estimated middle line closely for both. The middle panel is harder. The estimated inflation response stays negative longer than the model’s does. Matching how long inflation stays low is the weak spot.
They then asked what different rules would do. In their model, a better rule stabilizes inflation more and output less than the policy the Fed was estimated to follow.
The Zero Bound
The other paper I want to cover is Eggertsson and Woodford (2003), on the zero lower bound. Yes, 2003. It was in response to Japan already having near-zero interest rates, weak growth, and falling prices, but proved much more relevant after 2008.
What can a central bank do when its usual tool, cutting the rate, is gone?
We can think through this with the New Keynesian model. The zero bound is a price floor that the nominal interest rate can’t go below, but we have all these other parts of the equation. We have the distinction between real and nominal rates. We have to think about future policy expectations, and that turns out to be the key one.
The central bank can promise to keep rates low even after the zero-bound constraint stops binding. That changes the income and returns households expect, so they can spend more today.
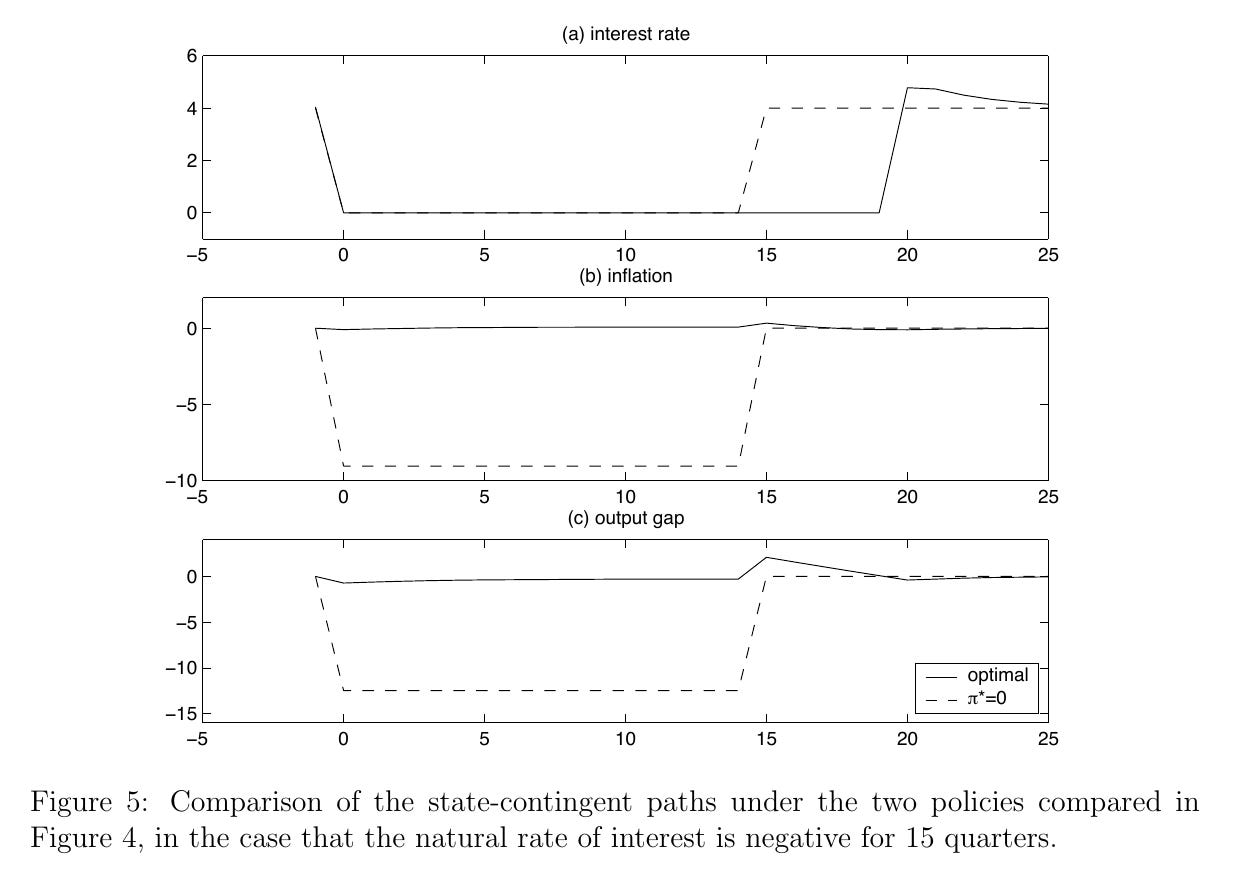
We can’t run experiments on the Fed. We only see the policies central banks actually chose, never what would have happened under the others. A model that gets household and firm behavior right lets us change the rule and follow the responses through spending, prices, and expectations.
Overall, Woodford and the New Keynesian model are the benchmark for these types of thought experiments.
This is a long post already, so I’m not going to go through my gripes with the New Keynesian model. I’d simply refer people to John Cochrane on the issues with how the model determines inflation at all. The model has no money. See Ricardo Lagos on whether we can safely ignore money, and to Josh on whether we are measuring it right.
That is great price theory in the Milton Friedman tradition, and I’m especially happy with Hall’s half of this prize. The model is wrong in plenty of ways. But a model like this gives us something concrete to argue about.
For more on prizes in this series, read last year’s on Mokyr, Aghion, and Howitt, the 2024 prize, and the 2023 prize.